U.S. Senate Fails to Advance CLARITY Act: What the Vote Means for Crypto
For years, one of the strangest things about the American cryptocurrency industry has been its size compared with the uncertainty surrounding the rules under which it operates, because companies can raise billions of dollars, investors can trade digital assets around the clock, and traditional financial institutions can build increasingly sophisticated crypto products while still confronting basic questions about which regulator is responsible for which part of the market.
The latest attempt by Congress to settle some of those questions has now run into a significant obstacle.
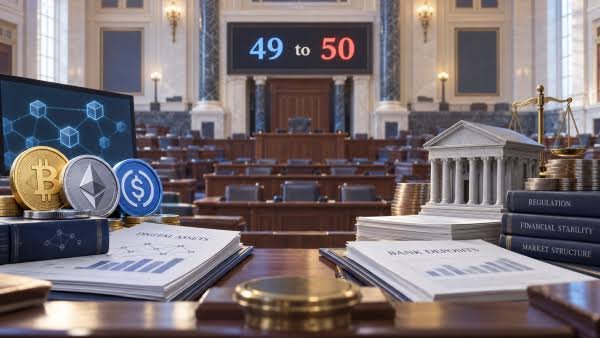
On September 15, the U.S. Senate failed to advance the Digital Asset Market CLARITY Act, a wide-ranging market-structure bill that was intended to establish a clearer federal framework for digital assets and define more precisely how responsibility should be divided among financial regulators. The legislation received majority support in the procedural vote but failed to reach the 60 votes required to move forward in the Senate.
That does not necessarily mean the legislation is dead, because Senate procedure leaves room for reconsideration, but it does mean that one of the crypto industry’s biggest legislative priorities remains unresolved at a time when regulators are already moving ahead with their own rules.
What was the CLARITY Act trying to fix?
The fundamental problem is surprisingly simple: the United States has several financial regulators whose responsibilities were designed long before cryptocurrency existed, and digital assets do not always fit neatly into the categories those agencies were originally created to supervise.
A token may function as a means of accessing a blockchain network, behave like a commodity in an open market, be sold as part of an investment arrangement, or represent ownership of a conventional financial asset, which means the legal treatment can depend as much on how the asset is issued and sold as on the technology underlying it.
Two agencies have been particularly important in this debate: the Securities and Exchange Commission and the Commodity Futures Trading Commission.
The CLARITY Act was designed in part to establish clearer boundaries between those regulators and create a federal market structure that crypto businesses could use when deciding how to issue, trade and custody digital assets.
Without legislation that settles those boundaries permanently, a considerable amount depends on interpretations and rules developed by the agencies themselves.
Why did the bill fail to advance?
The Senate vote reflected several disagreements rather than a single dispute, with lawmakers divided over the appropriate regulatory structure, the treatment of stablecoins and the broader relationship between the crypto industry, banks and federal financial regulators.
Banking groups have raised concerns about some forms of stablecoin rewards and the possibility that crypto products could compete directly with deposits traditionally held by banks, while some lawmakers have argued that the proposed framework requires stronger protections or different restrictions before it moves forward.
The politics surrounding cryptocurrency have also become more complicated as the industry has increased its spending and involvement in Washington, making what was once a relatively technical regulatory debate increasingly connected to wider disagreements about financial policy and political influence. Reuters reported that the industry’s political organizations had spent heavily supporting candidates viewed as favorable to digital-asset legislation, yet the Senate result demonstrated that substantial political spending does not automatically translate into legislative agreement.
Whatever view one takes of those arguments, the immediate consequence is the same: Congress has not yet established the durable market structure many participants had hoped would emerge in 2026.
This does not mean crypto regulation has stopped
It would be easy to interpret the failed Senate vote as meaning the United States has returned to regulatory paralysis, but that would miss what has changed during 2026.
In March, the SEC issued an interpretation describing how federal securities laws apply to several categories of crypto assets and transactions, while the CFTC provided related guidance under the Commodity Exchange Act. The SEC has since proposed a separate framework called Regulation Crypto Assets, which would create tailored pathways for certain crypto-related investment contracts.
In other words, Congress and the regulators are working on two different clocks.
Congress can create legislation that survives changes in presidential administrations and agency leadership, while regulators can interpret and administer the laws they already have, meaning the absence of a new statute does not prevent the SEC or CFTC from shaping the market in the meantime.
That distinction matters because regulatory certainty produced by an agency rule is not necessarily the same thing as certainty produced by legislation.
Markets noticed the vote
The Senate result arrived during an already sensitive period for cryptocurrency markets, with Bitcoin facing pressure from changing interest-rate expectations and investors closely watching Washington for signs that a clearer regulatory framework was approaching.
Reuters reported declines in Bitcoin and crypto-related companies including Coinbase and Circle following the Senate vote, although it would be an oversimplification to attribute every market movement to one piece of legislation, particularly when cryptocurrency prices are simultaneously responding to interest rates, Treasury yields, ETF flows and broader risk appetite.
That is an important distinction whenever political news moves financial markets.
A legislative setback can change expectations, but markets rarely have only one reason for moving.
What happens now?
The most important thing to watch is whether Senate leaders attempt to revive the legislation through negotiations that address the objections responsible for its failure to advance, because the procedural outcome does not prevent Congress from returning to the issue later.
Meanwhile, regulators are unlikely to wait.
The SEC’s proposed Regulation Crypto Assets remains part of the developing federal framework, and existing rules governing securities, commodities, taxation, anti-money-laundering requirements and financial intermediaries continue to apply where relevant.
For crypto users, the practical lesson is therefore less dramatic than the headlines might suggest: the CLARITY Act did not become law, but neither did American crypto regulation suddenly disappear.
The more interesting story is that the United States is now trying to build crypto regulation through two channels at once, with agencies interpreting existing laws while Congress continues debating what the permanent framework should look like.
That process has become slower again.
It has not stopped.